AI for internal audit: moving from sampling to full-population testing
Why sampling is no longer enough
Sampling was designed for a world where testing every transaction was too expensive. With ledger extracts and AI-assisted analysis, auditors can now test full populations for many risks in the time a sample used to take.
Full-population testing finds low-frequency, high-value exceptions that samples often miss, such as duplicate payments or journals posted at unusual times.
Five tests to run on the full population
| Test | What it finds |
|---|---|
| Duplicate payments | Same vendor, amount and date, or near-matches |
| Journal entry red flags | Weekend or late-night postings, round amounts, unusual users |
| Approval limit breaches | Purchase orders above the approver's limit |
| Split invoices | Invoices split to stay under approval thresholds |
| Vendor master anomalies | Vendors sharing bank accounts or addresses with employees |
AI training for Audit & Compliance
Where AI helps most
- Writing and explaining analytics scripts in Python or Excel
- Classifying exceptions and prioritising them for review
- Summarising policies and process documents during planning
- Drafting observations with root cause and recommendation
Keeping it audit-grade
Every AI-assisted procedure should be linked to an assessed risk, have a documented logic, and be reviewed. Keep the scripts, inputs and outputs in the working papers so a reviewer can re-perform the test.
Never let an AI tool be the only check on a number that goes into a report.
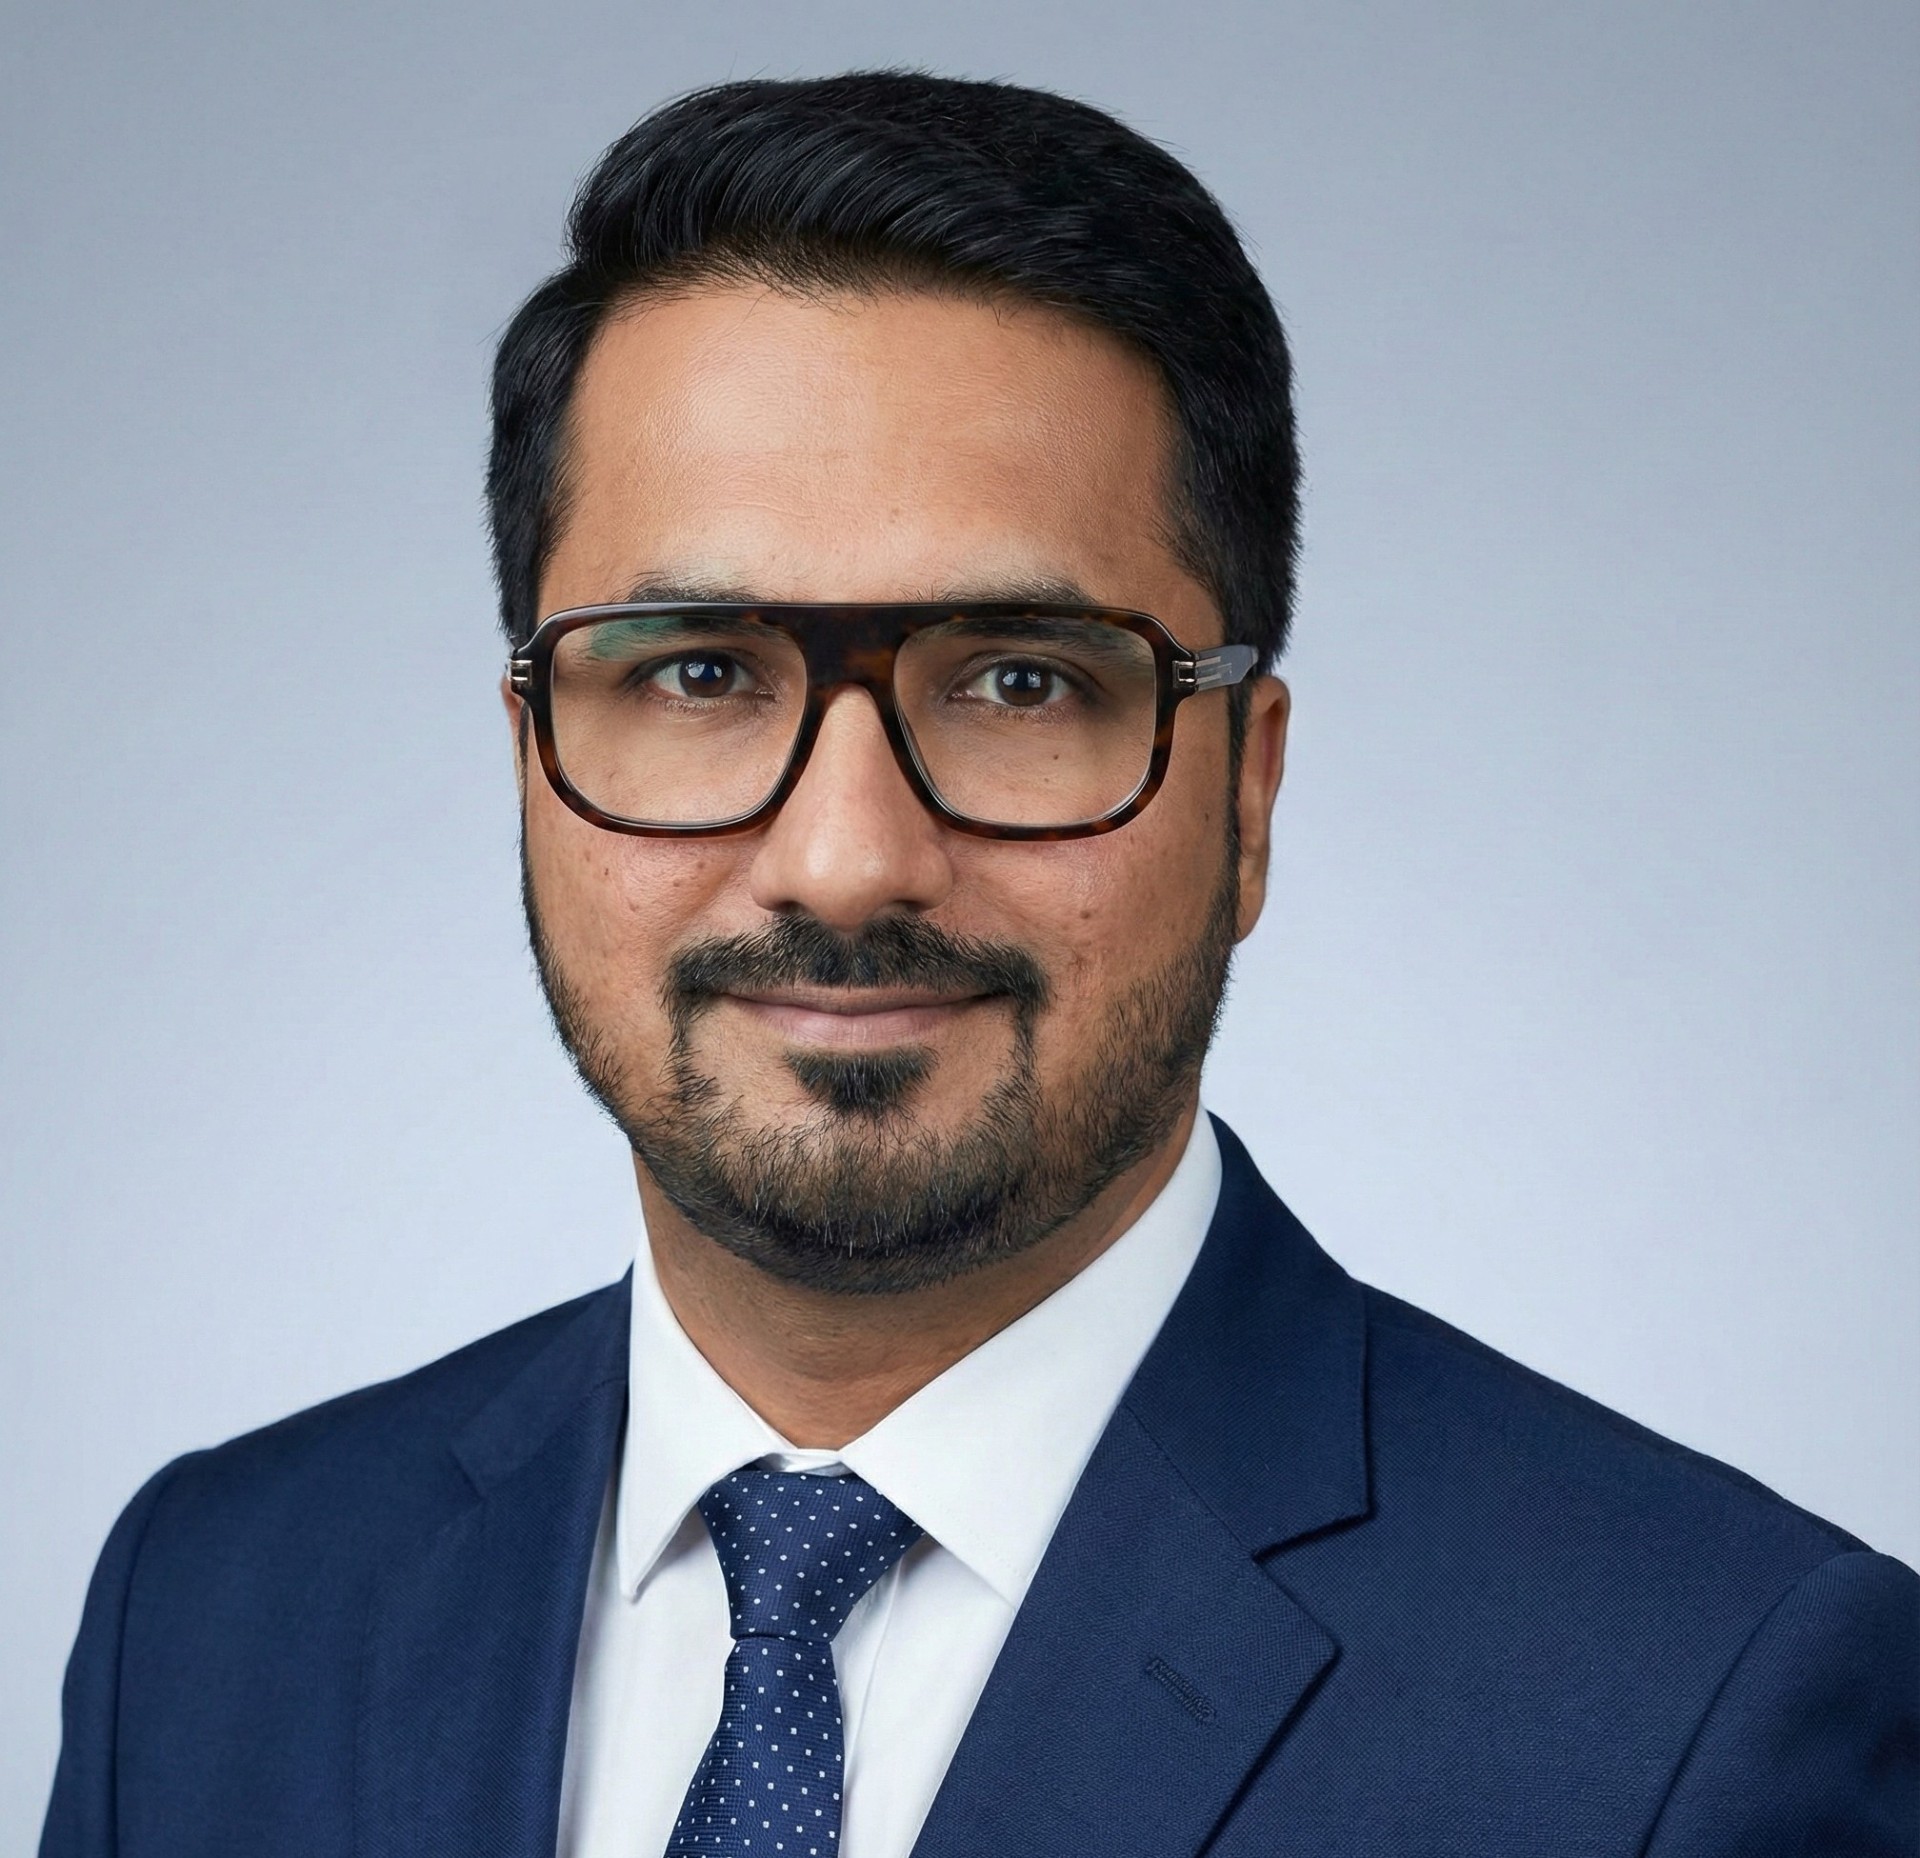
CA Dhaval Kodilkar is a corporate AI trainer, Fellow Chartered Accountant, Perplexity AI Business Fellow and ICAI AICA course architect. He has trained 20,000+ professionals across 9 countries.
Full profile